Louisiana Fortify Homes Program Round 3 Opens November 6

Louisiana REALTORS® • November 2, 2023

Applicants Strongly Encouraged to Review Eligibility Information Before Applying

Commissioner Jim Donelon announced November 1, 2023, that the Louisiana Fortify Homes Program (LFHP) will open its third round of grants at noon on November 6. There are 750 grants available in the third round, and grants will be awarded on a first-come, first-served basis. This round of grants is open to all homeowners whose home meets the criteria required for upgrading to the FORTIFIED Roof™ standard.


The LFHP provides grants of up to $10,000 for homeowners to repair or replace their roofs to the FORTIFIED Roof™ standard of the Insurance Institute for Business & Home Safety (IBHS). More information is available at www.ldi.la.gov/fortifyhomes. Those interested in the program are encouraged to review eligibility information and frequently asked questions on the LFHP website cited above to determine whether their home meets the requirements for the program.


Homeowners are required to create a profile in the LFHP system before applying for a grant and may do so by visiting www.ldi.la.gov/fortifyhomes. LFHP staff urge homeowners who are interested in the program to create a profile before the grant application period opens, as homeowners will need to log in to their profile before applying on November 6. Eligible homeowners should attempt to apply as quickly as possible once the application window goes live at noon.


The LFHP began with enough funding to award approximately 3,000 grants. The first half of those grants were limited to Citizens policyholders, and the remaining grants will be available to all homeowners across the state.


The grant will cover the cost of reinforcing a roof using methods that meet or exceed the FORTIFIED Roof™ standard, which includes strengthening a building against severe storms, high winds and wind driven rain. Homeowners must meet eligibility requirements and pay all costs for the roof upgrade including permits, inspections and construction costs beyond the amount of the grant.


Eligibility Requirements:

  • Homeowners are only eligible for their primary residence and must verify they have a homestead exemption on the property if selected for a grant. 
  • Homeowners must provide proof of an active residential insurance policy with wind coverage if selected for a grant. If they live in a Special Flood Hazard Area as designated by FEMA, they must also provide proof of a flood insurance policy. Contact your agent if you are unsure whether you have these coverages. 
  • New construction homes, condominiums and mobile homes do not qualify. 
  • Homes on a foundation constructed of unrestrained stacked masonry or stone (dry-stack foundation) are not eligible without an approved retrofit of the foundation. 
  • Homes must be in good repair as determined by a FORTIFIED™ Evaluator. Homeowners are responsible for hiring and paying the evaluation fee, which is typically between $300 and $500. 
  • Grant funds are paid directly to contractors. Homeowners are financially responsible for all costs beyond the full grant amount. Grant funding is limited to construction costs. 
  • These and all other eligibility requirements and program details may be reviewed at www.ldi.la.gov/fortifyhomes.
By Louisiana REALTORS® • October 9, 2026
Homeownership Is on Louisiana's November Ballot
By Louisiana REALTORS® • October 8, 2026
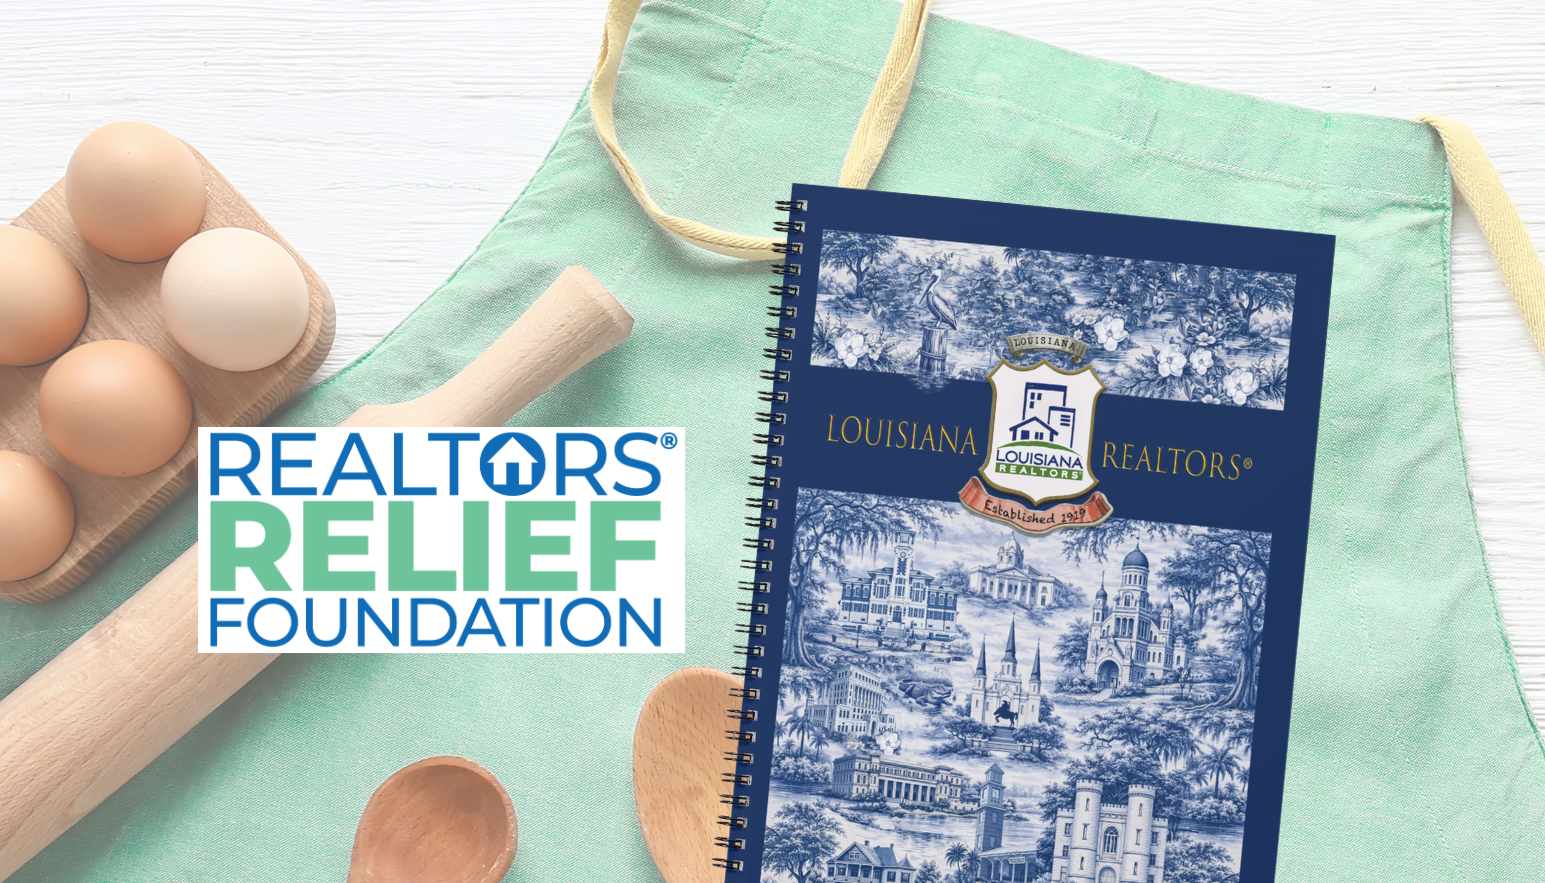
After months of gathering recipes from across our Louisiana REALTORS® family, the cookbook is ready! This 200+ page collection is filled with Louisiana flavor, REALTOR® heart and recipes contributed by our members. We launched sales of the cookbook at the Fall Governance Meetings. You can now purchase your copy for $30 directly from the printer and shipped to you! Additionally, we will have copies available at the RRF booth at NXT . After NXT, we will carry a limited stock at the LR office for you to purchase through the LR Merch Shop and pick-up from the office or at an LR event, as stock is available. Even better, $15 from every cookbook sold will be donated to the REALTORS® Relief Foundation (RRF) to help provide housing-related assistance to REALTORS® and their families following disasters. Pick up a copy for yourself, grab one as a gift and enjoy a taste of Louisiana while supporting a great cause!
By Louisiana REALTORS® • October 7, 2026
A major change to residential appraisal reporting is approaching, but a recently announced temporary policy exception is creating some confusion about what happens on November 2. Here is what REALTORS® need to know. Beginning November 2, 2026, Fannie Mae and Freddie Mac will require the new Uniform Appraisal Dataset (UAD) 3.6 for new appraisal reports initially submitted to the Uniform Collateral Data Portal (UCDP), unless the lender has received a temporary policy exception. The November 2 implementation date has not been postponed. What is the UAD 3.6 Appraisal Report? UAD 3.6 replaces the familiar legacy appraisal forms (used for the last 25 years) with a new, more data-driven appraisal report that collects much more detailed property information. For REALTORS® and consumers, the transition could mean a more detailed property inspection, additional questions about the property and transaction, and potentially longer appraisal and review times as appraisers, lenders, appraisal management companies, and other industry participants adjust to the new system. What changed? Fannie Mae and Freddie Mac recently announced a temporary policy exception for eligible lenders that need additional time to complete their transition to UAD 3.6. Lenders receiving the exception may continue submitting appraisals using the current legacy UAD 2.6 format through May 19, 2027 . Beginning May 20, 2027 , new appraisal submissions to Fannie Mae and Freddie Mac must use UAD 3.6. What does this mean for REALTORS®? For several months, REALTORS® may encounter both the current appraisal format and the new UAD 3.6 appraisal report. The appraisal format is determined by the lender's assignment requirements. REALTORS® and consumers do not need to determine which format should be used. It is also important to understand that an appraiser completing a legacy-format appraisal during this period should not automatically be assumed to be unprepared for UAD 3.6. An appraiser who is fully UAD 3.6 ready may still be instructed by a lender to complete an assignment using the legacy format. How can REALTORS® help? Good communication and accurate property information will become even more important. REALTORS® can help the appraisal process by providing accurate and specific information concerning: Recent renovations and improvements Property features and amenities Sales concessions and financing terms Known property conditions or unique characteristics Relevant information about the transaction Buyers should also be encouraged to discuss appraisal requirements and anticipated timelines with their lender early in the transaction. What about FHA, VA and USDA? The November 2 requirement discussed above applies to Fannie Mae and Freddie Mac conventional lending. FHA, VA and USDA have their own appraisal policies and implementation schedules. Their transition to UAD 3.6 should not be assumed to follow the same November 2 timeline unless announced by the respective agency. The Bottom Line November 2 remains an important date for UAD 3.6. The temporary exception does not cancel or postpone the transition. Instead, it allows eligible lenders additional time to complete their transition. As a result, REALTORS® should expect a period when both legacy and UAD 3.6 appraisal reports are being used. Louisiana REALTORS® will continue monitoring the transition and providing members with updates as additional guidance becomes available. Louisiana REALTORS® is also planning a follow-up webinar to discuss the latest UAD 3.6 developments, what REALTORS® are seeing in transactions, and what these changes mean for agents and their clients.
Show More