The Importance of Hiring a REALTOR®: Understanding Who They ‘R’ and What They Do

Louisiana REALTORS • May 15, 2024

Real estate transactions are likely the biggest and most significant financial decisions that you’ll make during your life. Whether you are buying your first home, selling a property, or you’ve been on both sides of the closing table, having a knowledgeable, professional resource on your side is critical. This is why hiring a REALTOR® is so important. Representing their clients and acting as a true fiduciary is what REALTORS® are trained to do, and it is all based on their Code of Ethics. While many people can pass a course in order to be eligible to sell real estate, the level of service that home buyers and sellers demand and deserve requires the commitment, experience, and expertise of an official REALTOR®, but what’s the difference?


The key difference in performance and ability that sets a REALTOR® apart is the NAR’s Code of Ethics. Every leading organization or group of professionals has a foundation that represents what they stand for. Without these foundations the legacy, integrity, advantage, competitive difference, and drive toward continued improvement is nearly impossible to have. For professional real estate agents, specifically REALTORS®, this foundation is the REALTOR® Code of Ethics. 


The REALTOR® Code of Ethics provides the highest safety measures for protecting both buyers and sellers of real estate. Being bound by this code as a REALTOR® creates a distinct competitive advantage. The REALTOR® Code of Ethics features 17 articles containing detailed rules and standards of conduct. It is designed to ensure that REALTORS® will act accordingly in a number of scenarios and situations; protecting their clients with competency and integrity, and also protecting the esteemed reputation of the National Association of REALTORS®.  The core of this code of ethics is to act in a way that protects all of the interests of whom a REALTOR® represents. The expectation is to use all available knowledge and experience and apply it to every transaction. Achieving the best possible results for a client is the focus of the REALTOR® Code of Ethics.


Beyond that guiding principle, the rest of the articles included in the Code are constructed to achieve the client’s goals. Overarching themes of honesty, cooperation, communication, and fairness are interwoven into the Code. The REALTOR® Code of Ethics is vitally important to real estate professionals, and especially to buyers and sellers of real estate as it provides the peace of mind that their best interests are at the root of every action.


Beyond the Code of Ethics comes the skill, talent, and expertise that REALTORS® possess and employ on behalf of their clients. These abilities, coupled with NAR’s strict Code of Ethics, means that you can have the peace of mind that your best interests and goals are at the forefront of every decision. While a REALTOR’S® fiduciary duty is the overarching benefit of your relationship, here are some more specific benefits of working with a REALTOR.


Contracts and Negotiations

Real estate transactions include complex and complicated legal processes. Having someone represent you that not only understands these processes, but that can inform, advise, and negotiate to ensure that your investment is as successful as possible.


Market Expertise and Consultation

If you’re shopping for a new house, your job is to know what you want. Your REALTOR’S® job is to know where to find it. If you’re selling your home, it is their job to get you the best price possible in a timely manner. Both sides of this transaction are improved when you have someone on your side that understands the market. There are a lot of other factors that go into the purchase or sale of home other than the number of bedrooms and total square feet. Being familiar with property tax regulations, school districts, nearby amenities, and many other elements all provide a much clearer picture for you as a client.


Real Estate Regulations

Staying current on changing real estate laws can be a full-time job in itself. If you are moving from state-to-state or simply across town, there can be a wide array of laws and regulations that you need to be aware of. This is your REALTOR’S® job. They are well-versed, and immersed in real estate regulations and will be aware of any and all pertinent information for your transaction.

FIND A REALTOR

This blog has been updated for accuracy and relevance from the original post.
By Louisiana REALTORS® • October 9, 2026
Homeownership Is on Louisiana's November Ballot
By Louisiana REALTORS® • October 8, 2026
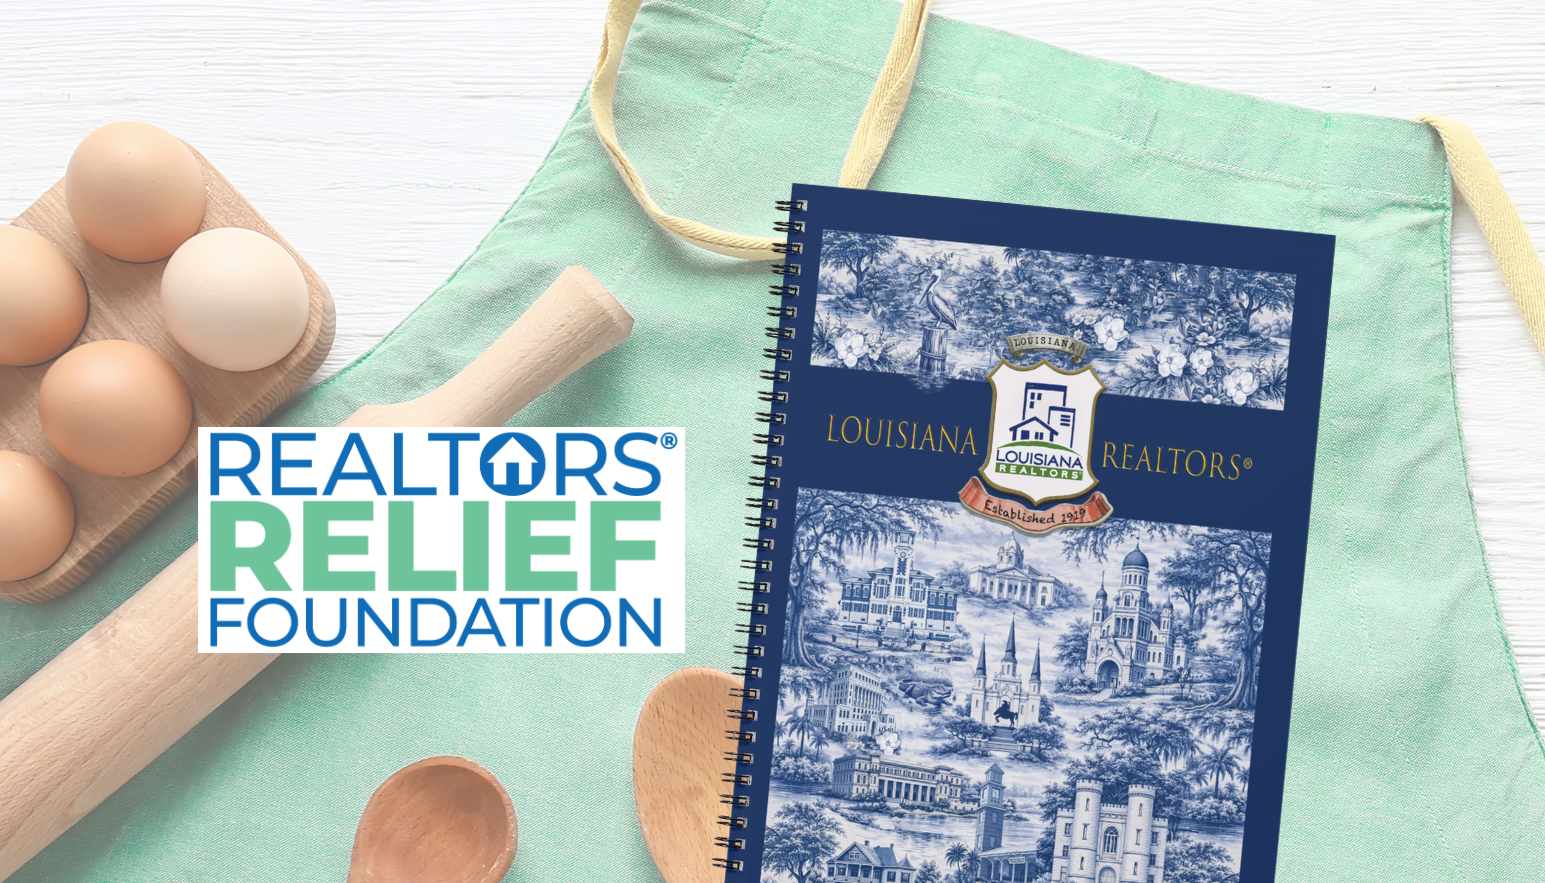
After months of gathering recipes from across our Louisiana REALTORS® family, the cookbook is ready! This 200+ page collection is filled with Louisiana flavor, REALTOR® heart and recipes contributed by our members. We launched sales of the cookbook at the Fall Governance Meetings. You can now purchase your copy for $30 directly from the printer and shipped to you! Additionally, we will have copies available at the RRF booth at NXT . After NXT, we will carry a limited stock at the LR office for you to purchase through the LR Merch Shop and pick-up from the office or at an LR event, as stock is available. Even better, $15 from every cookbook sold will be donated to the REALTORS® Relief Foundation (RRF) to help provide housing-related assistance to REALTORS® and their families following disasters. Pick up a copy for yourself, grab one as a gift and enjoy a taste of Louisiana while supporting a great cause!
By Louisiana REALTORS® • October 7, 2026
A major change to residential appraisal reporting is approaching, but a recently announced temporary policy exception is creating some confusion about what happens on November 2. Here is what REALTORS® need to know. Beginning November 2, 2026, Fannie Mae and Freddie Mac will require the new Uniform Appraisal Dataset (UAD) 3.6 for new appraisal reports initially submitted to the Uniform Collateral Data Portal (UCDP), unless the lender has received a temporary policy exception. The November 2 implementation date has not been postponed. What is the UAD 3.6 Appraisal Report? UAD 3.6 replaces the familiar legacy appraisal forms (used for the last 25 years) with a new, more data-driven appraisal report that collects much more detailed property information. For REALTORS® and consumers, the transition could mean a more detailed property inspection, additional questions about the property and transaction, and potentially longer appraisal and review times as appraisers, lenders, appraisal management companies, and other industry participants adjust to the new system. What changed? Fannie Mae and Freddie Mac recently announced a temporary policy exception for eligible lenders that need additional time to complete their transition to UAD 3.6. Lenders receiving the exception may continue submitting appraisals using the current legacy UAD 2.6 format through May 19, 2027 . Beginning May 20, 2027 , new appraisal submissions to Fannie Mae and Freddie Mac must use UAD 3.6. What does this mean for REALTORS®? For several months, REALTORS® may encounter both the current appraisal format and the new UAD 3.6 appraisal report. The appraisal format is determined by the lender's assignment requirements. REALTORS® and consumers do not need to determine which format should be used. It is also important to understand that an appraiser completing a legacy-format appraisal during this period should not automatically be assumed to be unprepared for UAD 3.6. An appraiser who is fully UAD 3.6 ready may still be instructed by a lender to complete an assignment using the legacy format. How can REALTORS® help? Good communication and accurate property information will become even more important. REALTORS® can help the appraisal process by providing accurate and specific information concerning: Recent renovations and improvements Property features and amenities Sales concessions and financing terms Known property conditions or unique characteristics Relevant information about the transaction Buyers should also be encouraged to discuss appraisal requirements and anticipated timelines with their lender early in the transaction. What about FHA, VA and USDA? The November 2 requirement discussed above applies to Fannie Mae and Freddie Mac conventional lending. FHA, VA and USDA have their own appraisal policies and implementation schedules. Their transition to UAD 3.6 should not be assumed to follow the same November 2 timeline unless announced by the respective agency. The Bottom Line November 2 remains an important date for UAD 3.6. The temporary exception does not cancel or postpone the transition. Instead, it allows eligible lenders additional time to complete their transition. As a result, REALTORS® should expect a period when both legacy and UAD 3.6 appraisal reports are being used. Louisiana REALTORS® will continue monitoring the transition and providing members with updates as additional guidance becomes available. Louisiana REALTORS® is also planning a follow-up webinar to discuss the latest UAD 3.6 developments, what REALTORS® are seeing in transactions, and what these changes mean for agents and their clients.
Show More