Getting Your Credit in Shape to Get a Mortgage

Louisiana REALTORS® • July 11, 2024

Buying a home is one of the biggest financial commitments you will ever make. Getting a mortgage is a critical stage in this process, and getting a mortgage  with favorable terms depends in large part on your credit score. Lenders use your credit score to determine your creditworthiness, which affects the interest rates and terms of the loans they offer. Preparing your credit before applying for a mortgage can save you hundreds of dollars over the course of the loan.


Understanding Credit Scores

Your credit score is a numerical representation of your creditworthiness, typically ranging from 300 to 850. The higher your score, the better your creditworthiness in the eyes of lenders. Credit scores are calculated based on several factors:


  • Payment History (35%): Your record of on-time payments.
  • Credit Utilization (30%): The amount of credit you're using compared to your credit limits.
  • Length of Credit History (15%): The average age of your credit accounts.
  • Credit Mix (10%): The variety of credit types you have, such as credit cards, loans, and mortgages.
  • New Credit (10%): The number of recent credit inquiries and newly opened accounts.


Steps to Improve Your Credit Score

Review Your Credit Reports

Equifax, Experian, and TransUnion are the three main credit bureaus. Start by acquiring your credit reports from each. Every bureau is required to provide you with a free report once a year at AnnualCreditReport.com. Carefully check these reports for mistakes, such as inaccurate account information or fraudulent activity, and raise any discrepancies that you find.


Make Payments On Time

Your credit score is mostly influenced by the payment history you have provided. It's important to always pay your payments on time. For peace of mind, set up automated payments or reminders so you never forget a deadline. Your credit score can be severely impacted by even one late payment.


Cut Down on Credit Usage

The ratio of your outstanding credit card balances to your credit limits is known as credit usage. To raise your score, try to keep your utilization below 30%. Reduce your balances or ask for an increase in your credit limit, if at all possible (but avoid piling on extra debt).


Don't Create New Credit Accounts

Opening new credit accounts to increase your available credit may seem appealing, but doing so will temporarily drop your score because of hard queries and a decline in the average age of existing accounts. Create new accounts only when it is absolutely required.


Keep Your Old Credit Accounts Open

Keep older accounts open even if you don't use them much since your credit history matters. Your credit score may suffer if you close old accounts because doing so can decrease your credit history and lower your total amount of available credit.


Mix Up Your Credit

A variety of credit kinds, such as retail accounts, installment loans, and credit cards, can all help raise your score. However, only take on additional credit types if you can responsibly manage the payments and it makes sense for your financial condition.


Reduce Debt Wisely

Prioritize paying off high-interest debt in order to save money on interest and expedite the reduction of your total debt. To speed up your debt repayment, think about applying the avalanche or snowball methods, which pay off high-interest debt first and smaller balances last, respectively.


Keep an Eye on Your Credit

Use credit monitoring services to keep an eye on your credit record and score. Frequent monitoring keeps you updated on any changes to your credit score and warns you of any unusual activity that might have an impact on it.


Timing Your Mortgage Application

Work on raising your credit score well in advance of when you intend to apply for a mortgage, as it takes time. Try to start half a year or more in advance. You have this window of time to make adjustments and observe how they improve your credit score.


It's crucial to improve your credit before applying for a mortgage in order to get the best potential loan conditions. You can raise your creditworthiness and chances of acceptance by being aware of the elements that affect your credit score and taking proactive measures to raise it. Your REALTOR® and your lender can also provide helpful ways to make sure that your credit is in a place to get you the most favorable terms for your mortgage. 
RESOURCES FOR BUYING A HOME
By Louisiana REALTORS® • October 8, 2026
After months of gathering recipes from across our Louisiana REALTORS® family, the cookbook is ready! This 200+ page collection is filled with Louisiana flavor, REALTOR® heart and recipes contributed by our members. We launched sales of the cookbook at the Fall Governance Meetings. You can now purchase your copy for $30 directly from the printer and shipped to you! Additionally, we will have copies available at the RRF booth at NXT . After NXT, we will carry a limited stock at the LR office for you to purchase through the LR Merch Shop and pick-up from the office or at an LR event, as stock is available. Even better, $15 from every cookbook sold will be donated to the REALTORS® Relief Foundation (RRF) to help provide housing-related assistance to REALTORS® and their families following disasters. Pick up a copy for yourself, grab one as a gift and enjoy a taste of Louisiana while supporting a great cause!
By Louisiana REALTORS® • October 7, 2026
A major change to residential appraisal reporting is approaching, but a recently announced temporary policy exception is creating some confusion about what happens on November 2. Here is what REALTORS® need to know. Beginning November 2, 2026, Fannie Mae and Freddie Mac will require the new Uniform Appraisal Dataset (UAD) 3.6 for new appraisal reports initially submitted to the Uniform Collateral Data Portal (UCDP), unless the lender has received a temporary policy exception. The November 2 implementation date has not been postponed. What is the UAD 3.6 Appraisal Report? UAD 3.6 replaces the familiar legacy appraisal forms (used for the last 25 years) with a new, more data-driven appraisal report that collects much more detailed property information. For REALTORS® and consumers, the transition could mean a more detailed property inspection, additional questions about the property and transaction, and potentially longer appraisal and review times as appraisers, lenders, appraisal management companies, and other industry participants adjust to the new system. What changed? Fannie Mae and Freddie Mac recently announced a temporary policy exception for eligible lenders that need additional time to complete their transition to UAD 3.6. Lenders receiving the exception may continue submitting appraisals using the current legacy UAD 2.6 format through May 19, 2027 . Beginning May 20, 2027 , new appraisal submissions to Fannie Mae and Freddie Mac must use UAD 3.6. What does this mean for REALTORS®? For several months, REALTORS® may encounter both the current appraisal format and the new UAD 3.6 appraisal report. The appraisal format is determined by the lender's assignment requirements. REALTORS® and consumers do not need to determine which format should be used. It is also important to understand that an appraiser completing a legacy-format appraisal during this period should not automatically be assumed to be unprepared for UAD 3.6. An appraiser who is fully UAD 3.6 ready may still be instructed by a lender to complete an assignment using the legacy format. How can REALTORS® help? Good communication and accurate property information will become even more important. REALTORS® can help the appraisal process by providing accurate and specific information concerning: Recent renovations and improvements Property features and amenities Sales concessions and financing terms Known property conditions or unique characteristics Relevant information about the transaction Buyers should also be encouraged to discuss appraisal requirements and anticipated timelines with their lender early in the transaction. What about FHA, VA and USDA? The November 2 requirement discussed above applies to Fannie Mae and Freddie Mac conventional lending. FHA, VA and USDA have their own appraisal policies and implementation schedules. Their transition to UAD 3.6 should not be assumed to follow the same November 2 timeline unless announced by the respective agency. The Bottom Line November 2 remains an important date for UAD 3.6. The temporary exception does not cancel or postpone the transition. Instead, it allows eligible lenders additional time to complete their transition. As a result, REALTORS® should expect a period when both legacy and UAD 3.6 appraisal reports are being used. Louisiana REALTORS® will continue monitoring the transition and providing members with updates as additional guidance becomes available. Louisiana REALTORS® is also planning a follow-up webinar to discuss the latest UAD 3.6 developments, what REALTORS® are seeing in transactions, and what these changes mean for agents and their clients.
By Louisiana REALTORS® • October 7, 2026
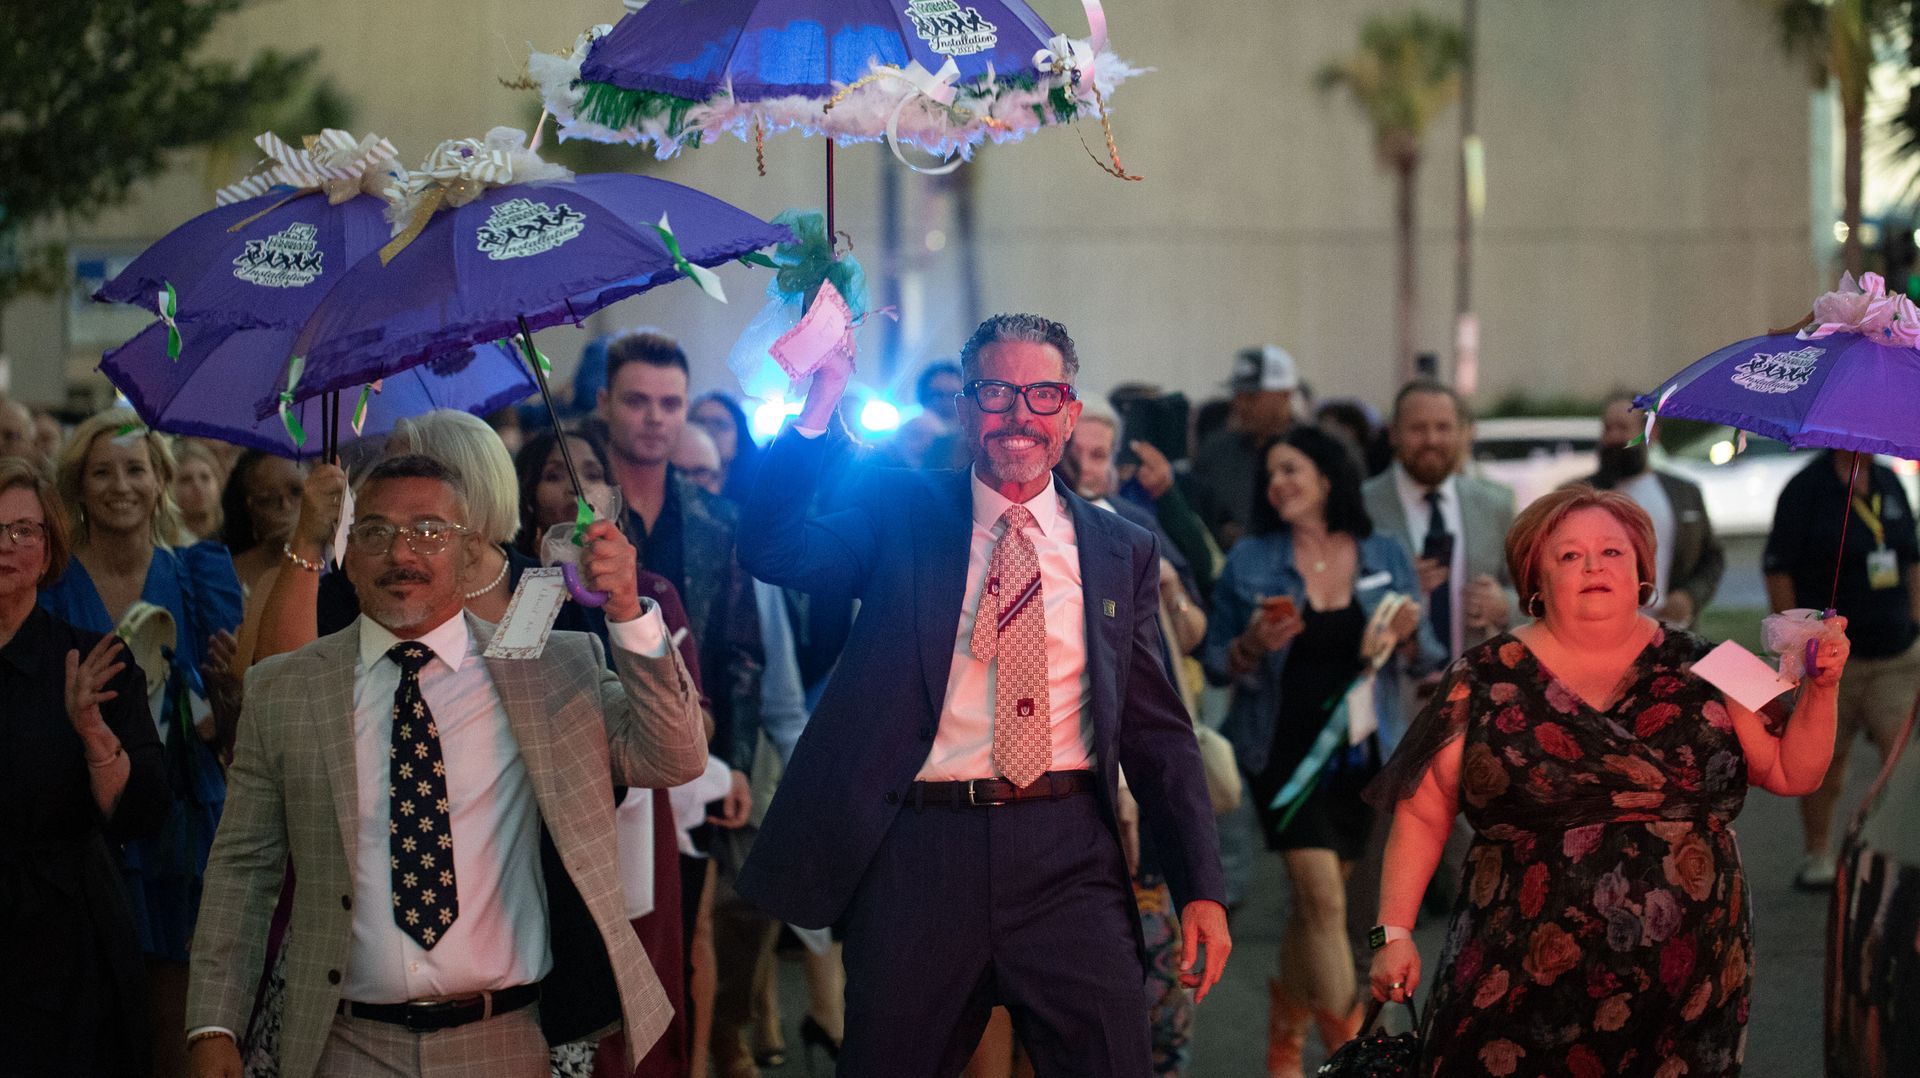
Louisiana REALTORS® wraps up the 2026 Fall Governance Meetings in New Orleans! Louisiana REALTORS® gathered in New Orleans September 29–October 1 at Harrah's Hotel Tower at Caesars for the 2026 Fall Governance Meetings, three days filled with professional development, governance, networking and celebration. The conference opened with the conclusion of the 2026 LR Leadership Program. Participants graduated from the yearlong program at a closing retreat, followed by a luncheon with LR officers. The 2026 graduates include: Meghan Adam, Scott Domingue, Nichole Donald, Herbert Dubuisson, Clint Galliano, Beth Graham, Ivan Jennings, Catice Johnson, Dana MacCord, Candy Modeen, Craig Morris, Ron Patron, Amber Reinking, David Rollins and Jennifer Tagliarino. That evening, the Welcome Reception at Stadium Club at Mannings celebrated the graduating class and brought back alumni from previous years for the LR Leadership Reunion. Tuesday's education kicked off with a live "Residential Real Estate Economic Update" from NAR Chief Economist Dr. Lawrence Yun, giving attendees an expert look at the trends shaping the market. Members who joined early for the Commercial Symposium on September 28 got a head start on the week. Wednesday brought a full day of learning and connection. After a breakfast buffet, Robert Siciliano led "CSI Protection: Cyber Social Identity and Personal Protection," equipping attendees to defend themselves and their clients against today's cyber threats. The Town Hall Luncheon followed, along with the Local AE Meeting and the YPN Open Meeting with Panel Discussion. Leigh Brown's "Fearless Agents" session gave REALTORS® the confidence and strategies to stand out in a shifting market. Wednesday night, members celebrated the 2027 Louisiana REALTORS® Officer Installation with a ceremony followed by The Sidewalk Step Second Line through the streets of New Orleans to Vue Orleans, where the evening continued with a reception. Thursday opened with Leigh Brown's "Next is Now," a session on rebuilding trust through availability, action and discipline. Regional caucuses followed, and the Board of Directors Meeting brought the governance portion of the event to a close. At the meeting, Cindy Dyer, [Northwest]; Mark Ouchley, [Northeast]; Lacy Baaeth, [Greater Baton Rouge]; Bill Boyd, [Bayou]; Marsha McGraw-Barbera, [Greater Central] and Candy Modeen, [Northshore] were elected as 2027 At-Large Directors. They will join the 2027 Board in helping guide the association and represent REALTORS® from across the state, serving a two year term. Attendees could also earn up to six hours of CE throughout the conference. Louisiana REALTORS® looks forward to hosting REALTORS® from around the state at the Winter Conference at the Golden Nugget in Lake Charles . We would like to thank our sponsors for their generous support in helping make this conference happen! Our Vue From the Top Sponsor: New Orleans Metropolitan Association of REALTORS® (NOMAR); Grand Marshall Sponsors: American Home Shield, Arena Collective, First American Exchange Company and Guard Home Warranty; Second Line Sponsor: Zillow; Brass Band Backer Sponsor: REALTOR® Association of Acadiana and Roy Appraisals, Inc.; and Sidewalk Stepper Sponsors: Bayou Board of REALTORS®, Bob Brooks School, Compass Inspection Services, LLC, Expert Insurance Services (EIS), LLC, Goosehead Insurance Brandon Katz, Greater Central REALTORS® Association, Hartwig Moss Insurance Agency and Women’s Council of REALTORS® New Orleans Metropolitan Area.
Show More