
Necessary Documentation and Privacy Considerations
LOUISIANA REALTORS • April 1, 2020
CORONAVIRUS: NECESSARY DOCUMENTATION AND PRIVACY CONSIDERATIONS[1]
By: Patricia B. McMurray, JD and Melissa M. Grand, JD
Baker, Donelson, Bearman, Caldwell & Berkowitz, PC
450 Laurel Street, Chase Tower North, 21st Floor
Baton Rouge, Louisiana 70801
In this uncertain time, it is critical that REALTORS® consider what paperwork related to COVID-19 they should be maintaining. Federal loan programs, like the new CARES Act, and other grant programs require that certain documents be submitted in the application process to prove the loss sustained as a result of the pandemic. You might have business interruption insurance or be eligible for other new programs that are still being formulated if you can show your lost income. Not having proper documentation may mean not being able to apply for or receive certain loans, grants, or other funds. Additionally, REALTORS® may be collecting confidential documentation, such as health information in a coronavirus screening questionnaire from clients, employees, and independent contractors. REALTORS® also store personal and confidential information of clients and employees during the regular course of their business. Maintaining the confidentiality and security of this information obtained by your business is important.
1. What documentation should I be keeping as I consider applying for various reimbursement programs, loans, grants, business interruption insurance or other sources of funding?
Short Answer:
In addition to your general record-keeping practices, we suggest that you maintain documentation of any COVID-19 related expenses or losses separately from other payments and expenses, if possible.
The CARES Act created two new Small Business Administration (SBA) initiatives: the SBA 7(a) “Payroll Protection Program” and the SBA “Economic Injury Disaster Loan” (EIDL) grant program. Visit SBA's Disaster Assistance website for more detailed information on these programs. See also, the National Association of REALTORS®’ (NAR) guidance on the CARES Act
and REALTOR® Magazine article on new small business loans. As the U.S. Chamber of Commerce guidance
explains, in evaluating eligibility under the CARES Act, lenders will ask for a good faith certification that the uncertainty of current economic conditions makes the loan request necessary to support ongoing operations. It is a best practice to maintain detailed documentation of your COVID-19 related payments and expenses separately from your regular business payments and expenses, for your use in demonstrating the economic impact of COVID-19 on your business. For example, emails, copies of texts or correspondence related to closings which were canceled because of delays related to the Governor’s Stay Home Orders, documentation of canceled open houses, etc. should be retained.
Other information you may be asked to provide in applying for a loan under the CARES Act includes basic identifying information for your business, your business TIN number, your average monthly payroll, the number of jobs supported by your company and what specifically you want to use the loan money for. See Treasury.gov. You will also be asked to list all owners who hold at least a 20 percent ownership stake in the company and affirm that they are not party to federal crimes. See id. Also, you may be asked to provide the lender with documentation regarding your employee headcount over time, as well as your payroll costs. Tax returns may also be required.
2. I am requesting that all clients complete a coronavirus questionnaire before they enter a property I am showing. I am also asking my employees and independent contractors to complete a coronavirus questionnaire form and self-report if they have been exposed to coronavirus. What should I do with these completed forms?
Short Answer: You should maintain a copy of the screening forms when completed. Keep the completed forms secure and confidential such as in a locked filing cabinet or password-protected electronic file.
The information collected on the screening forms may contain medical information and should be treated as confidential. The National Association of REALTORS® guidance on general document retention may be found here. Also Louisiana REALTORS® (LR) discussed coronavirus screening questionnaires and provided sample questions in LR’s article on hold harmless agreements, here.
3. What are my obligations to generally maintain documents?
Short Answer: You must maintain certain records for 5 years pursuant to the real estate license law. Keep the documents properly indexed, and secure (physically secure, for example in locked cabinets, and/or electronically secure) to preserve client privacy and confidentiality.
LA. R. S. §1449D1 provides:
D. (1) Individual real estate brokers shall retain all of the following records, readily available and properly indexed, for a period of five years:
(a) Bank statements, copies of deposit slips, and canceled checks on all escrow or trust accounts.
(b) Copies of all documents that pertain in any way to real estate transactions wherein the individual real estate broker or licensees sponsored by the individual real estate broker have appeared in a licensing capacity.
(2) The requirement regarding copies shall not be altered by the transfer of a broker to that of an associate broker, an unlicensed person, or an inactive licensee.
E.(1) Partnerships, limited liability companies, associations, corporations, or other legal entities, foreign or domestic, and real estate brokers shall retain the following records, readily available and properly indexed, for a period of five years:
(a) Bank statements, copies of deposit slips, and canceled checks on all escrow or trust accounts.
(b) Copies of all documents that pertain in any way to real estate transactions wherein the partnership, limited liability company, association, corporation, or other legal entity, foreign or domestic, the designated qualifying broker, or licensees sponsored by same, have appeared in a licensing capacity.
(2) This requirement, regarding copies, shall not be altered by the partnership, limited liability company, association, corporation, or other legal entity, foreign or domestic, transferring the broker license to the inactive status or failure to renew such license.
All businesses, including real estate firms, should have policies and procedures in place for keeping client information secure and disposing of consumer information in a manner that preserves client privacy and confidentiality. A comprehensive data security plan will ensure that businesses collect only the consumer information needed, keep the information safe, and dispose of the information securely.
There is no one-size-fits all approach to data security and compliance, but many resources exist to assist businesses in complying with their legal responsibilities. Available resources include:
DISCLAIMER
Information and additional guidance and orders regarding the pandemic are being issued daily. The information is the article was last updated on April 1, 2020 at 12:30 p.m.
These materials are to be used for informational purposes and should not be construed as specific legal advice. These materials are not designed to cover every aspect of a legal situation for every factual circumstance that may arise regarding the subject matter included.
This publication is for reference purposes only and association members or other readers are responsible for contacting their own attorneys or other professional advisors for legal or contract advice. The comments provided herein solely represent the opinions of the authors and is not a guarantee of interpretation of the law or contracts by any court or by the Louisiana Real Estate Commission.
A major change to residential appraisal reporting is approaching, but a recently announced temporary policy exception is creating some confusion about what happens on November 2. Here is what REALTORS® need to know. Beginning November 2, 2026, Fannie Mae and Freddie Mac will require the new Uniform Appraisal Dataset (UAD) 3.6 for new appraisal reports initially submitted to the Uniform Collateral Data Portal (UCDP), unless the lender has received a temporary policy exception. The November 2 implementation date has not been postponed. What is the UAD 3.6 Appraisal Report? UAD 3.6 replaces the familiar legacy appraisal forms (used for the last 25 years) with a new, more data-driven appraisal report that collects much more detailed property information. For REALTORS® and consumers, the transition could mean a more detailed property inspection, additional questions about the property and transaction, and potentially longer appraisal and review times as appraisers, lenders, appraisal management companies, and other industry participants adjust to the new system. What changed? Fannie Mae and Freddie Mac recently announced a temporary policy exception for eligible lenders that need additional time to complete their transition to UAD 3.6. Lenders receiving the exception may continue submitting appraisals using the current legacy UAD 2.6 format through May 19, 2027 . Beginning May 20, 2027 , new appraisal submissions to Fannie Mae and Freddie Mac must use UAD 3.6. What does this mean for REALTORS®? For several months, REALTORS® may encounter both the current appraisal format and the new UAD 3.6 appraisal report. The appraisal format is determined by the lender's assignment requirements. REALTORS® and consumers do not need to determine which format should be used. It is also important to understand that an appraiser completing a legacy-format appraisal during this period should not automatically be assumed to be unprepared for UAD 3.6. An appraiser who is fully UAD 3.6 ready may still be instructed by a lender to complete an assignment using the legacy format. How can REALTORS® help? Good communication and accurate property information will become even more important. REALTORS® can help the appraisal process by providing accurate and specific information concerning: Recent renovations and improvements Property features and amenities Sales concessions and financing terms Known property conditions or unique characteristics Relevant information about the transaction Buyers should also be encouraged to discuss appraisal requirements and anticipated timelines with their lender early in the transaction. What about FHA, VA and USDA? The November 2 requirement discussed above applies to Fannie Mae and Freddie Mac conventional lending. FHA, VA and USDA have their own appraisal policies and implementation schedules. Their transition to UAD 3.6 should not be assumed to follow the same November 2 timeline unless announced by the respective agency. The Bottom Line November 2 remains an important date for UAD 3.6. The temporary exception does not cancel or postpone the transition. Instead, it allows eligible lenders additional time to complete their transition. As a result, REALTORS® should expect a period when both legacy and UAD 3.6 appraisal reports are being used. Louisiana REALTORS® will continue monitoring the transition and providing members with updates as additional guidance becomes available. Louisiana REALTORS® is also planning a follow-up webinar to discuss the latest UAD 3.6 developments, what REALTORS® are seeing in transactions, and what these changes mean for agents and their clients.
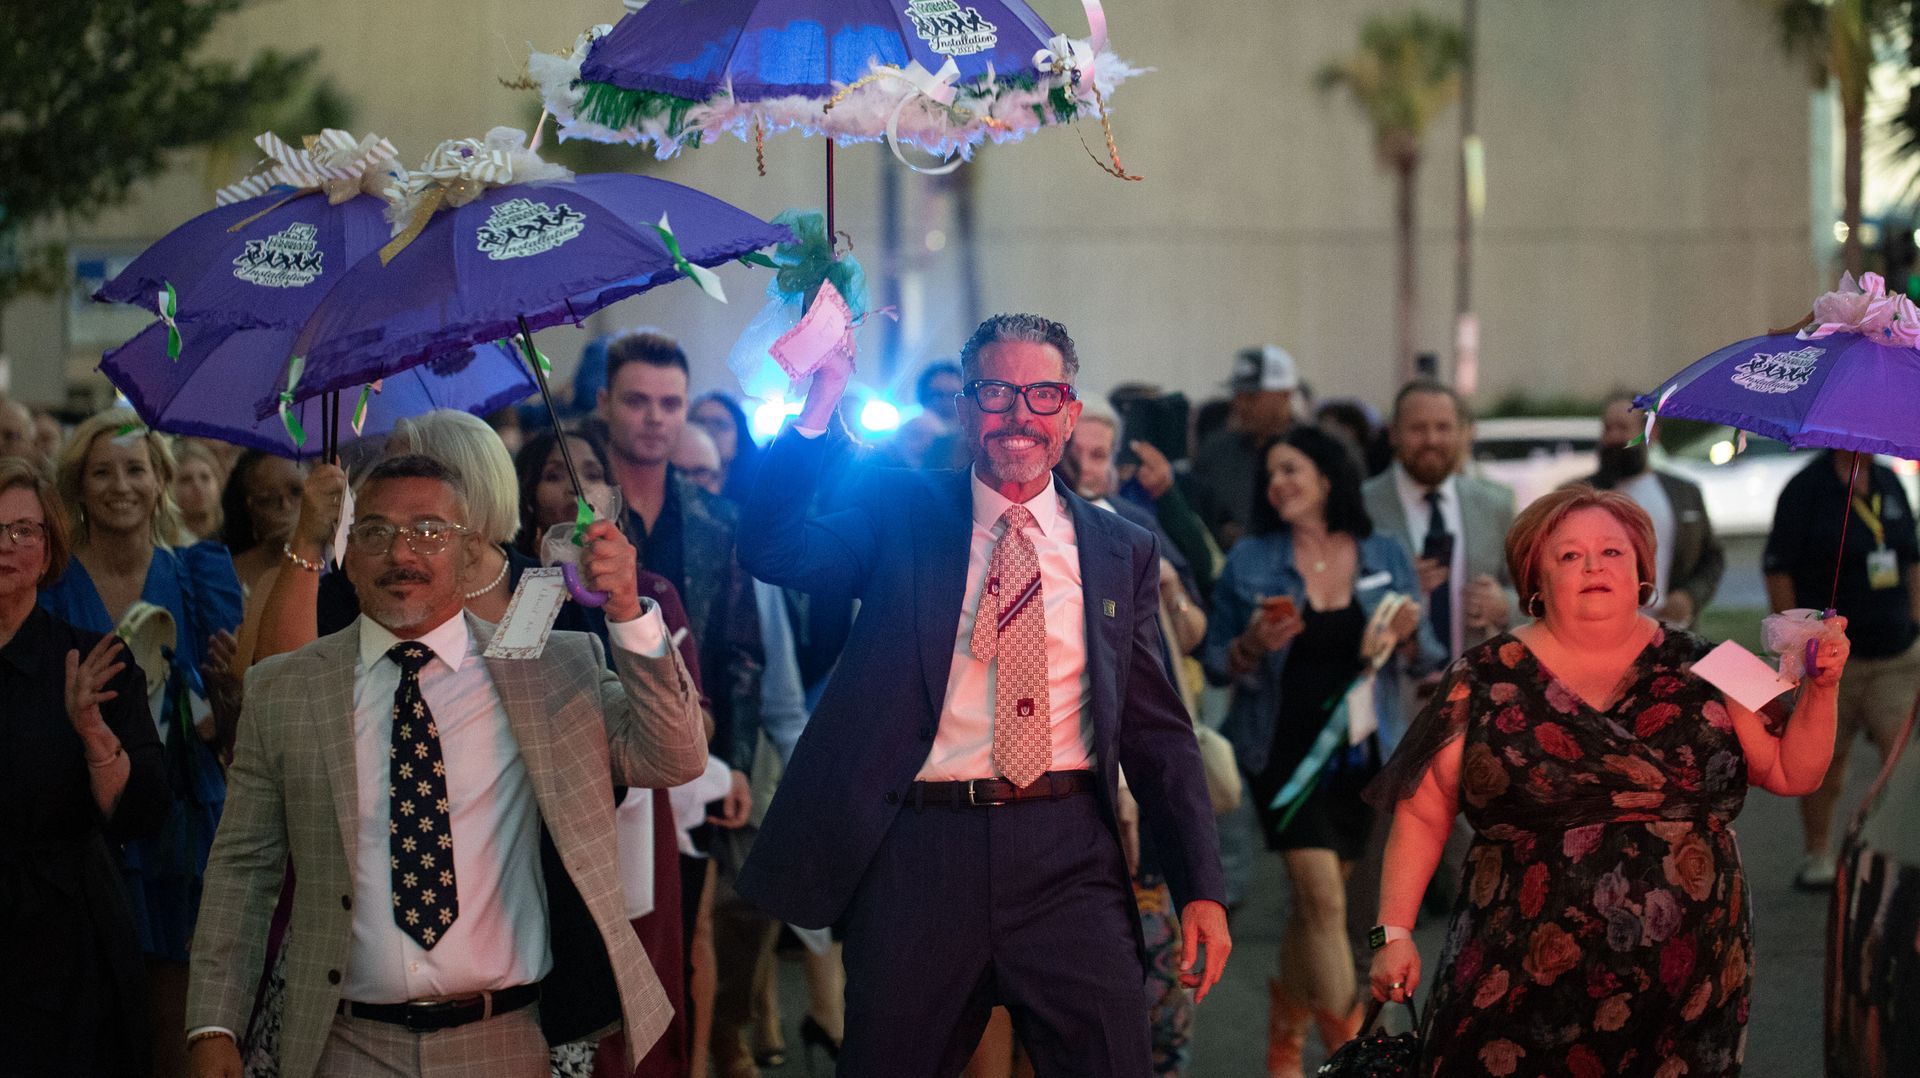
Louisiana REALTORS® wraps up the 2026 Fall Governance Meetings in New Orleans! Louisiana REALTORS® gathered in New Orleans September 29–October 1 at Harrah's Hotel Tower at Caesars for the 2026 Fall Governance Meetings, three days filled with professional development, governance, networking and celebration. The conference opened with the conclusion of the 2026 LR Leadership Program. Participants graduated from the yearlong program at a closing retreat, followed by a luncheon with LR officers. The 2026 graduates include: Meghan Adam, Scott Domingue, Nichole Donald, Herbert Dubuisson, Clint Galliano, Beth Graham, Ivan Jennings, Catice Johnson, Dana MacCord, Candy Modeen, Craig Morris, Ron Patron, Amber Reinking, David Rollins and Jennifer Tagliarino. That evening, the Welcome Reception at Stadium Club at Mannings celebrated the graduating class and brought back alumni from previous years for the LR Leadership Reunion. Tuesday's education kicked off with a live "Residential Real Estate Economic Update" from NAR Chief Economist Dr. Lawrence Yun, giving attendees an expert look at the trends shaping the market. Members who joined early for the Commercial Symposium on September 28 got a head start on the week. Wednesday brought a full day of learning and connection. After a breakfast buffet, Robert Siciliano led "CSI Protection: Cyber Social Identity and Personal Protection," equipping attendees to defend themselves and their clients against today's cyber threats. The Town Hall Luncheon followed, along with the Local AE Meeting and the YPN Open Meeting with Panel Discussion. Leigh Brown's "Fearless Agents" session gave REALTORS® the confidence and strategies to stand out in a shifting market. Wednesday night, members celebrated the 2027 Louisiana REALTORS® Officer Installation with a ceremony followed by The Sidewalk Step Second Line through the streets of New Orleans to Vue Orleans, where the evening continued with a reception. Thursday opened with Leigh Brown's "Next is Now," a session on rebuilding trust through availability, action and discipline. Regional caucuses followed, and the Board of Directors Meeting brought the governance portion of the event to a close. At the meeting, Cindy Dyer, [Northwest]; Mark Ouchley, [Northeast]; Lacy Baaeth, [Greater Baton Rouge]; Bill Boyd, [Bayou]; Marsha McGraw-Barbera, [Greater Central] and Candy Modeen, [Northshore] were elected as 2027 At-Large Directors. They will join the 2027 Board in helping guide the association and represent REALTORS® from across the state, serving a two year term. Attendees could also earn up to six hours of CE throughout the conference. Louisiana REALTORS® looks forward to hosting REALTORS® from around the state at the Winter Conference at the Golden Nugget in Lake Charles . We would like to thank our sponsors for their generous support in helping make this conference happen! Our Vue From the Top Sponsor: New Orleans Metropolitan Association of REALTORS® (NOMAR); Grand Marshall Sponsors: American Home Shield, Arena Collective, First American Exchange Company and Guard Home Warranty; Second Line Sponsor: Zillow; Brass Band Backer Sponsor: REALTOR® Association of Acadiana and Roy Appraisals, Inc.; and Sidewalk Stepper Sponsors: Bayou Board of REALTORS®, Bob Brooks School, Compass Inspection Services, LLC, Expert Insurance Services (EIS), LLC, Goosehead Insurance Brandon Katz, Greater Central REALTORS® Association, Hartwig Moss Insurance Agency and Women’s Council of REALTORS® New Orleans Metropolitan Area.
How can a REALTOR® help you get more value from your home purchase? Learn how REALTORS® can guide buyers through market research, negotiations, long-term value, and the homebuying process.