3 Essentials for Preventing Disputes

Amy P. Fennell • May 10, 2019

Information shared from Today’s Buyer’s Rep publication

Procuring cause is defined as “the uninterrupted series of casual events which results in a successful transaction. If a dispute does arise, your claim of entitlement to a commission hinges on several factors and will often times go through an arbitration or mediation process.

Avoiding trouble is quite simple. Just do the very best job possible!

All the vital details are covered in Accredited Buyer’s Representative (ABR) Designation Course but the following contains some good practices to implement in order to prevent disputes.

1) Educate Buyers

Procuring cause disputes often stem from misunderstandings. It’s up to you to instruct buyers about what they can expect from you (clien-level services) and what you expect from them (loyalty) during the course of the relationship. The more a buyer understands your role (and theirs), the less likely they’ll wander into the services of another agent.

The REALTOR Code of Ethics requires you to ask prospective buyers if they are party to an exclusive representation agreement. If yes, send them back to their buyer’s rep. If not, education them on buyer representation.

It’s always a good idea to ensure buyers understand the fiduciary nature of your relationship and their role in the process. Education goes a long way towardpreventing buyers from straying into a situation that could trigger a dispute.

2. Use Signed Agreements

A written and signed buyer representation agreement supports several goals. In particular; it:

  • Sets expectations

  • Demonstrates the value you bring to the transaction

  • Encourages buyer loyalty

Misunderstandings are more likely to occur in the absence of a written agreement. Even though the state doesn’t require one, consider using it anyway. A buyer’s agreement will strengthen your position with a buyer because it spells out the terms of your agency relationship.

Did you know? If a dispute arises between brokers, a buyer representation agreement does not automatically mean the buyer’s agent is the procuring cause.

3. Walk the Talk

Buyers tend to be loyal if they know you’re working hard for them, so make sure you’re delivering against your verbal and written promises.

Document your efforts. If a disput arises, you’re in a much better position if you can demonstrate that you:

  • Stayed in regular contact during the time covered by your agreement

  • Searched for appropriate properties

  • Had conversations about potential properties

  • Kept the buyer informed of your efforts

  • Asked if the buyer became aware of properties of interest

Your buyer should know you are working for them even when there are no properties on the market that fits their needs. Otherwise, it’s easy for buyers to assume your relationship has ended (called “abandonment”.) Communication gaps increase the odds that another agent will fill the void.


This information is provided to ABR designees on a regular basis through the resource magazine. If you are interested in earning the Accredited Buyer Representative designation, Louisiana REALTORS is offering an opportunity to get the education in Shreveport, LA on May 30 - 31, 2019. For more information, click here.

If you have an interest in learning more about mediating disputes or becoming an ombudsman, LR is offering a course, Making Opposites Agree, as part of Career Development Week. For questions about education, please contact us at 1-800-266-8538.

By Louisiana REALTORS® • October 9, 2026
Homeownership Is on Louisiana's November Ballot
By Louisiana REALTORS® • October 8, 2026
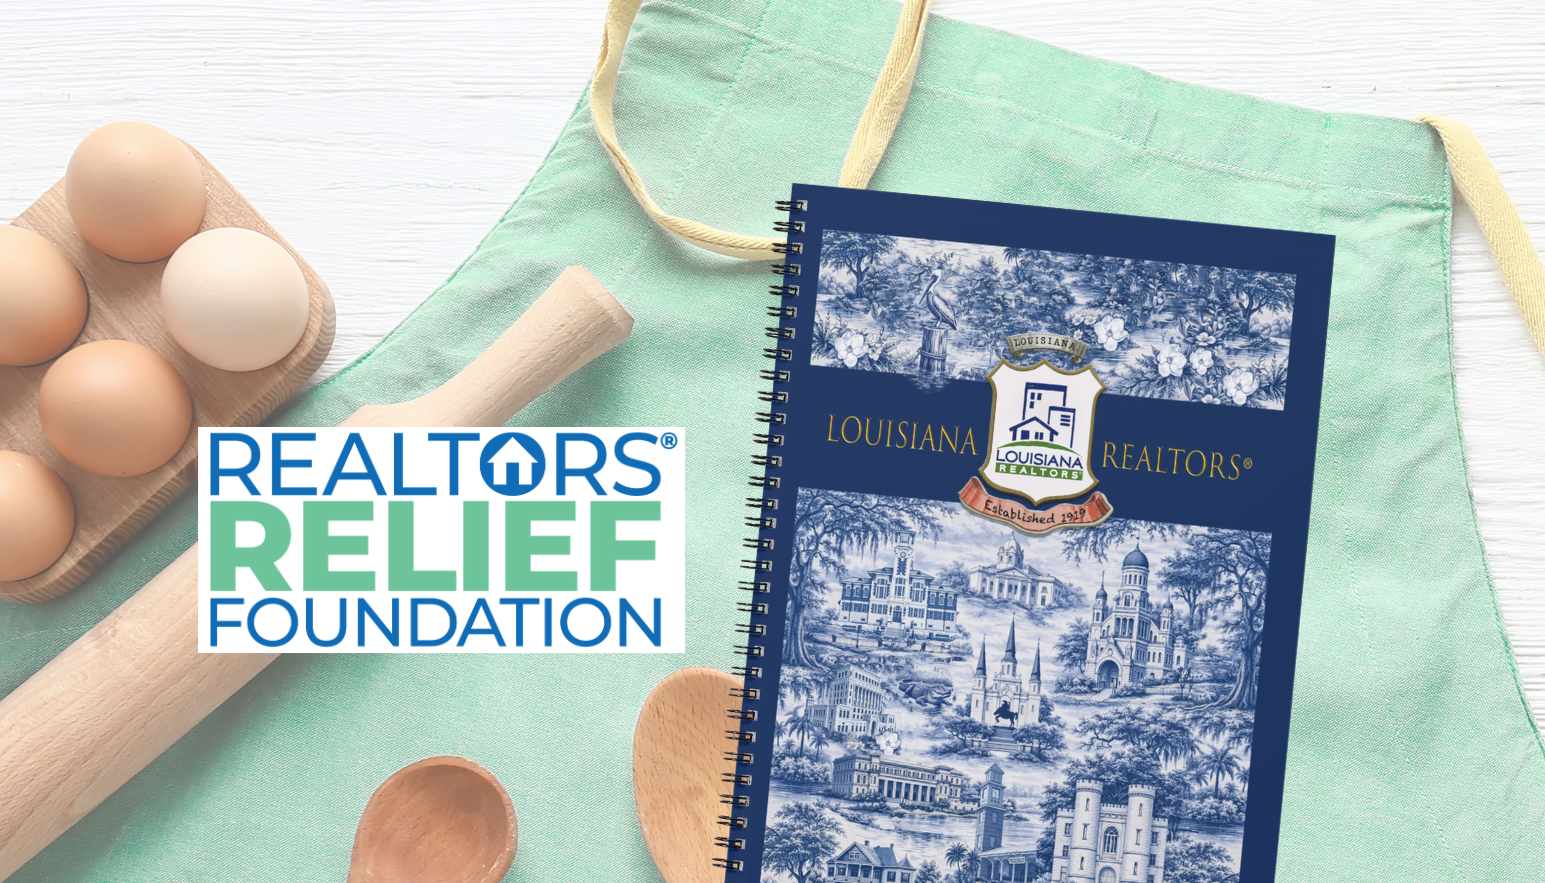
After months of gathering recipes from across our Louisiana REALTORS® family, the cookbook is ready! This 200+ page collection is filled with Louisiana flavor, REALTOR® heart and recipes contributed by our members. We launched sales of the cookbook at the Fall Governance Meetings. You can now purchase your copy for $30 directly from the printer and shipped to you! Additionally, we will have copies available at the RRF booth at NXT . After NXT, we will carry a limited stock at the LR office for you to purchase through the LR Merch Shop and pick-up from the office or at an LR event, as stock is available. Even better, $15 from every cookbook sold will be donated to the REALTORS® Relief Foundation (RRF) to help provide housing-related assistance to REALTORS® and their families following disasters. Pick up a copy for yourself, grab one as a gift and enjoy a taste of Louisiana while supporting a great cause!
By Louisiana REALTORS® • October 7, 2026
A major change to residential appraisal reporting is approaching, but a recently announced temporary policy exception is creating some confusion about what happens on November 2. Here is what REALTORS® need to know. Beginning November 2, 2026, Fannie Mae and Freddie Mac will require the new Uniform Appraisal Dataset (UAD) 3.6 for new appraisal reports initially submitted to the Uniform Collateral Data Portal (UCDP), unless the lender has received a temporary policy exception. The November 2 implementation date has not been postponed. What is the UAD 3.6 Appraisal Report? UAD 3.6 replaces the familiar legacy appraisal forms (used for the last 25 years) with a new, more data-driven appraisal report that collects much more detailed property information. For REALTORS® and consumers, the transition could mean a more detailed property inspection, additional questions about the property and transaction, and potentially longer appraisal and review times as appraisers, lenders, appraisal management companies, and other industry participants adjust to the new system. What changed? Fannie Mae and Freddie Mac recently announced a temporary policy exception for eligible lenders that need additional time to complete their transition to UAD 3.6. Lenders receiving the exception may continue submitting appraisals using the current legacy UAD 2.6 format through May 19, 2027 . Beginning May 20, 2027 , new appraisal submissions to Fannie Mae and Freddie Mac must use UAD 3.6. What does this mean for REALTORS®? For several months, REALTORS® may encounter both the current appraisal format and the new UAD 3.6 appraisal report. The appraisal format is determined by the lender's assignment requirements. REALTORS® and consumers do not need to determine which format should be used. It is also important to understand that an appraiser completing a legacy-format appraisal during this period should not automatically be assumed to be unprepared for UAD 3.6. An appraiser who is fully UAD 3.6 ready may still be instructed by a lender to complete an assignment using the legacy format. How can REALTORS® help? Good communication and accurate property information will become even more important. REALTORS® can help the appraisal process by providing accurate and specific information concerning: Recent renovations and improvements Property features and amenities Sales concessions and financing terms Known property conditions or unique characteristics Relevant information about the transaction Buyers should also be encouraged to discuss appraisal requirements and anticipated timelines with their lender early in the transaction. What about FHA, VA and USDA? The November 2 requirement discussed above applies to Fannie Mae and Freddie Mac conventional lending. FHA, VA and USDA have their own appraisal policies and implementation schedules. Their transition to UAD 3.6 should not be assumed to follow the same November 2 timeline unless announced by the respective agency. The Bottom Line November 2 remains an important date for UAD 3.6. The temporary exception does not cancel or postpone the transition. Instead, it allows eligible lenders additional time to complete their transition. As a result, REALTORS® should expect a period when both legacy and UAD 3.6 appraisal reports are being used. Louisiana REALTORS® will continue monitoring the transition and providing members with updates as additional guidance becomes available. Louisiana REALTORS® is also planning a follow-up webinar to discuss the latest UAD 3.6 developments, what REALTORS® are seeing in transactions, and what these changes mean for agents and their clients.
Show More